
Commentary
2026 Third Quarter Report
Following strong market returns in the second quarter, the third quarter ended largely flat after a mild pullback in September. The defining market event in the quarter was the Federal Reserve increasing interest rates by 0.25%, which was the first increase in three years, bringing the Fed Funds rate to the 3.75% to 4.0% range. Driven by persistent inflation, with the Consumer Price Index (CPI) rising to 3.40% as of its August reading, the bond market is now anticipating one additional rate hike in the fourth quarter this year and another in early 2027. This policy pivot along with higher oil prices caused the 10-year Treasury yield to surge in the quarter from 4.41% to 5.29%, which is a peak not seen since 2002.
Here is a summary of returns across the major categories in our client portfolios:
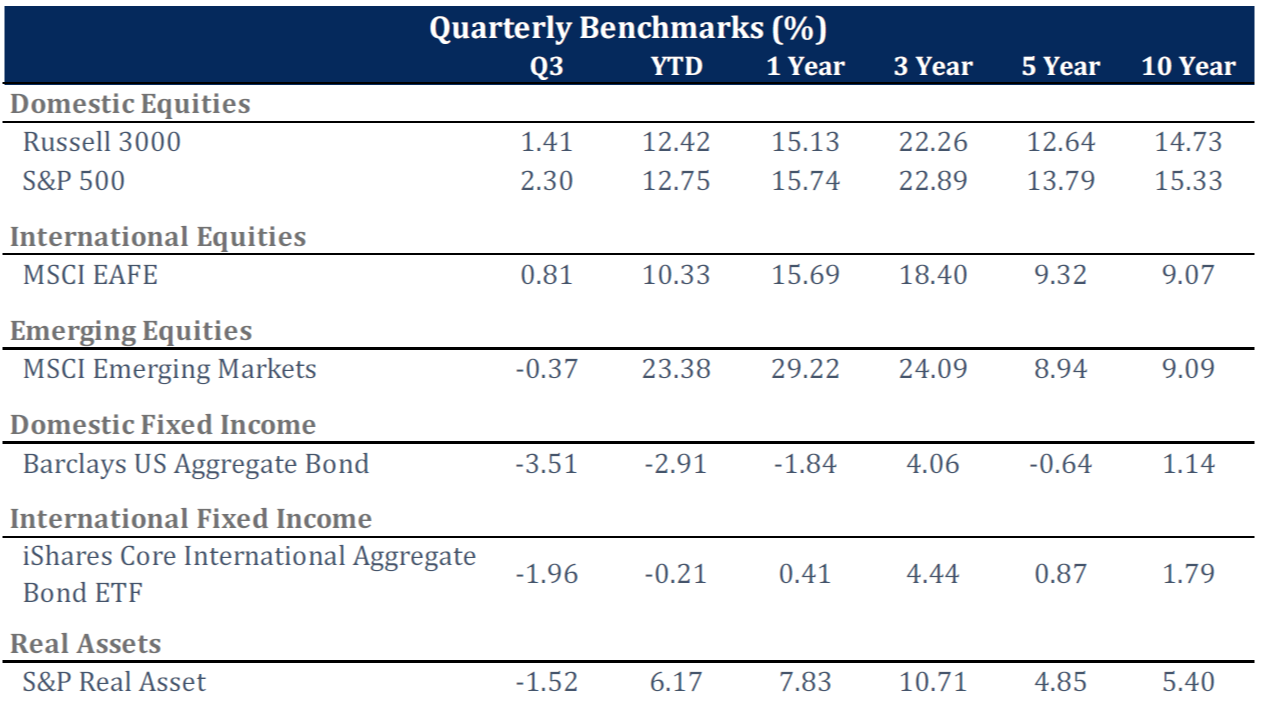
While the sudden rise in rates in September triggered the worst quarter for bonds since 2022 and led to a dip in stocks, today’s market environment is healthier than it was during the last Federal Reserve hiking cycle. In 2022, bonds yielded a meager 2%, leaving investors vulnerable to rising rates. Today, our taxable bond funds yield roughly 5.75% and tax-free municipal bonds yield around 4.10%. These higher yields provide a substantial cushion and margin of safety, shortening the time required to recoup recent bond price drops. Furthermore, the upside for bonds is substantial: if the 10-year Treasury were to drop to just 4.50%, taxable bonds could generate a total return near 10% over a 12-month horizon, restoring their role as an excellent portfolio diversifier.
Housing is one part of the economy that is the most sensitive to higher interest rates. The average 30-year fixed-rate mortgage has climbed to 7.50%, increasing the cost of ownership for borrowers and new homeowners. While home prices have held steady, houses are now staying on the market for longer, indicating softening demand from buyers. Available housing inventory has increased to 4.6 months of supply, marking the highest level since the Covid-19 pandemic.
Conversely, the stock market has exhibited resiliency in the face of higher rates as strong growth continues to power the market. Technology was up 7% for the quarter, and analysts expect profits for tech companies to grow a remarkable 44% over the next year, which is well above historical averages. Energy, which our portfolios have exposure to via large value funds, was up another 17% for the quarter, pushing the sector’s year-to-date gain to over 40%. Looking beyond these sectors, the S&P 500 Index has grown profits 29% over the past year, greatly exceeding the historical average of 8% growth. Growth is not just falling through to the bottom line either as revenue over the coming year is expected to grow by 12%, which is double the 10- year average. Such strong growth has resulted in the S&P 500 Index trading for a valuation below its recent peaks all while the bull market continues.
While entering a new rate-hiking cycle can bring short-term discomfort, it is important to remember that every period in the markets is different with its own set of unique challenges and opportunities. The trend for stocks has largely been positive, and it is not unusual for stocks and interest rates to move higher together when driven by a healthy economy and robust consumer spending. Higher bond yields today bolster the safe side of portfolios and compensate investors for being patient until stocks resume making new all-time highs. We stand ready to navigate these challenges and take advantage of the opportunities while achieving your goals and securing your long-term financial future.
Sincerely,
Your Harbor Group Team